

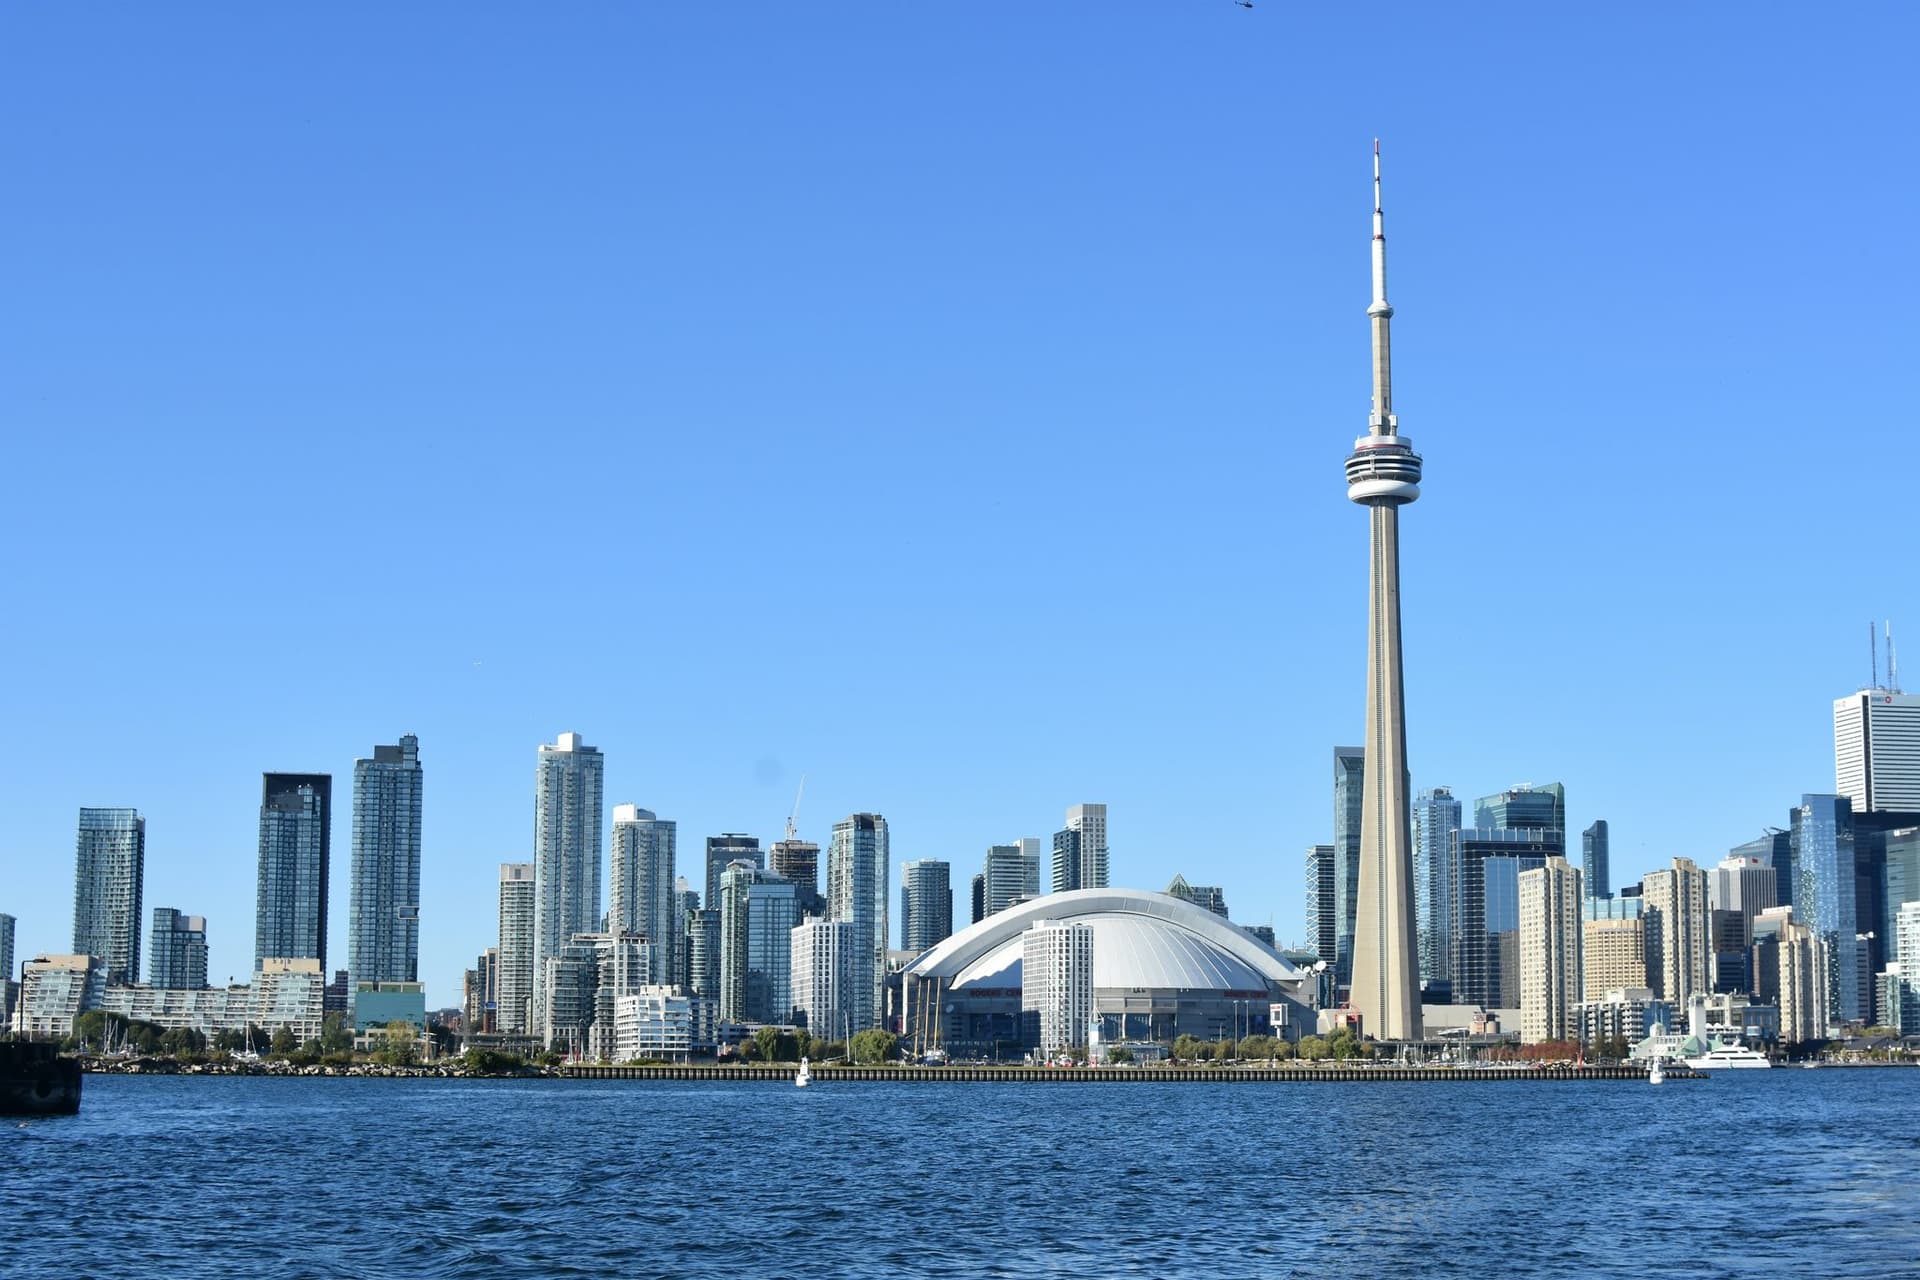
Toronto, ON
Canada’s housing market entered the second half of the year in a more stable position than it held earlier in the spring. Sales have risen for three consecutive months, the national benchmark price stopped declining in June, and available supply is now close to its long-term level.
That improvement has not developed into a broad recovery. Sales remain subdued by historical standards, benchmark prices are still below last year’s levels, and a weakening construction pipeline is becoming a more significant part of the housing outlook.
Resale Activity Has Improved Since Spring
June marked a third consecutive monthly increase in national home sales. Activity rose 0.5% from May, following increases of 5.5% in May and 0.9% in April, according to the Canadian Real Estate Association. That left sales about 7% above their March level. Actual June transactions were also 0.9% higher than a year earlier.
Prices are showing signs of stabilization as well. June was the first month since January 2025 in which the National Composite MLS® Home Price Index did not decline from the previous month. On an annual basis, the index remained 3.6% below June 2025, although the gap had narrowed to its smallest since October.
The non-seasonally adjusted national average home price moved differently, rising 0.5% annually to $696,078. That measure can be affected by changes in where transactions are taking place, so the increase does not mean values are rising uniformly across the country.
June ended with 208,578 active listings across Canadian MLS® Systems, only 0.6% more than a year earlier and 0.8% above the long-term average for that point in the year. At 4.8 months, inventory was at its lowest level of 2026 and remained close to the long-term average of five months.
New listings declined for a second consecutive month, helping push the national sales-to-new-listings ratio to 50.2%. The figures point to a market that has moved away from the softer conditions of early spring without becoming unusually tight.
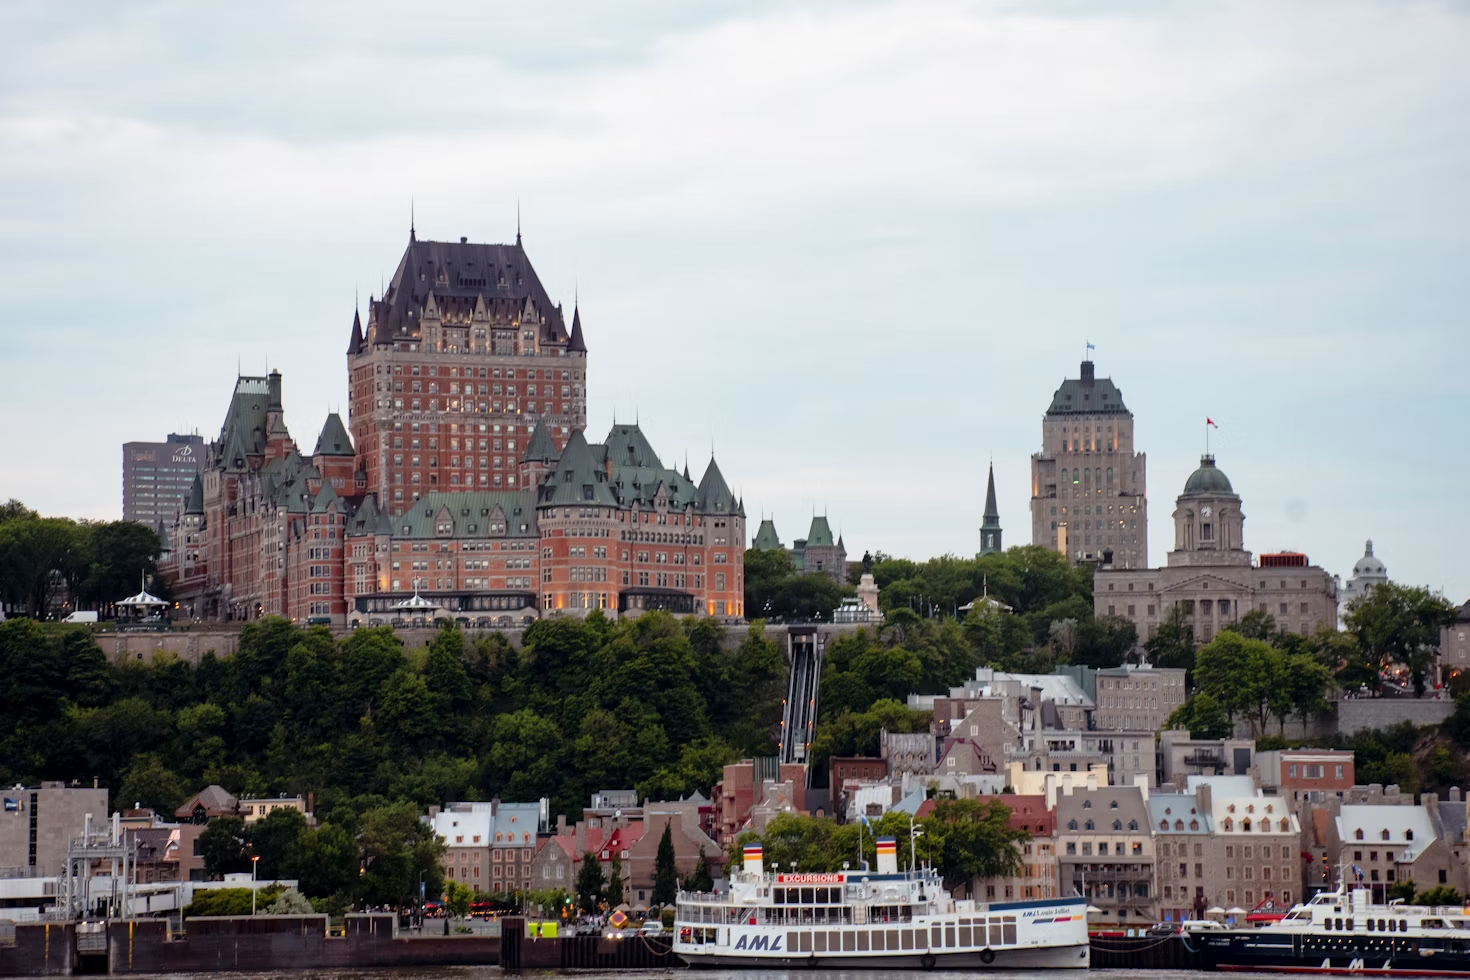
Québec, QC
SUBSCRIBE TO THE HAVEN MAILING LIST
Curated homes, market intelligence and design stories — a few emails a month.
No spam. Unsubscribe any time.
The 2026 Outlook Remains Restrained
The improvement since March has not erased the weak start to the year. In its July forecast, CREA lowered its projection for 2026 sales to 463,336 transactions, 1.4% below 2025. Ontario is now the only province expected to record an annual increase in sales.
CREA expects the national average home price to rise 1.1% this year to $686,710. Small declines in British Columbia and Ontario are expected to be offset by continued price growth elsewhere, including renewed gains in Alberta during the second quarter.
The Canada Mortgage and Housing Corporation’s mid-year outlook, released July 22, is more cautious. Its baseline forecast places the national average MLS® price at $675,200 in 2026, down from $679,543 last year. CMHC expects slow population growth, high borrowing costs, modest income gains, and economic uncertainty to continue limiting demand, but still anticipates a gradual improvement in sales over the next couple of years, with activity remaining below historical norms.
The two forecasts differ on whether the national average price will finish 2026 slightly higher or lower, but neither points to a rapid rebound. CREA expects annual sales to decline despite the recent improvement, while CMHC projects activity to remain below levels typically seen over the past decade.
Ontario and British Columbia Face Greater Pressure
CREA’s June market report states that benchmark prices remained below year-earlier levels in British Columbia, Alberta, and Ontario in June, although the declines in all three provinces have been narrowing. Nova Scotia also recorded its first annual decline in more than three years.
The outlook is particularly soft in Ontario and British Columbia. CMHC expects affordability pressures and slower population growth to continue weighing on both markets. CREA’s annual forecast similarly calls for average prices to decline by less than 1% in each province this year.
Conditions elsewhere are different. Alberta prices resumed rising during the second quarter, according to CREA, while Newfoundland and Labrador remains the only province firmly in seller’s-market territory.
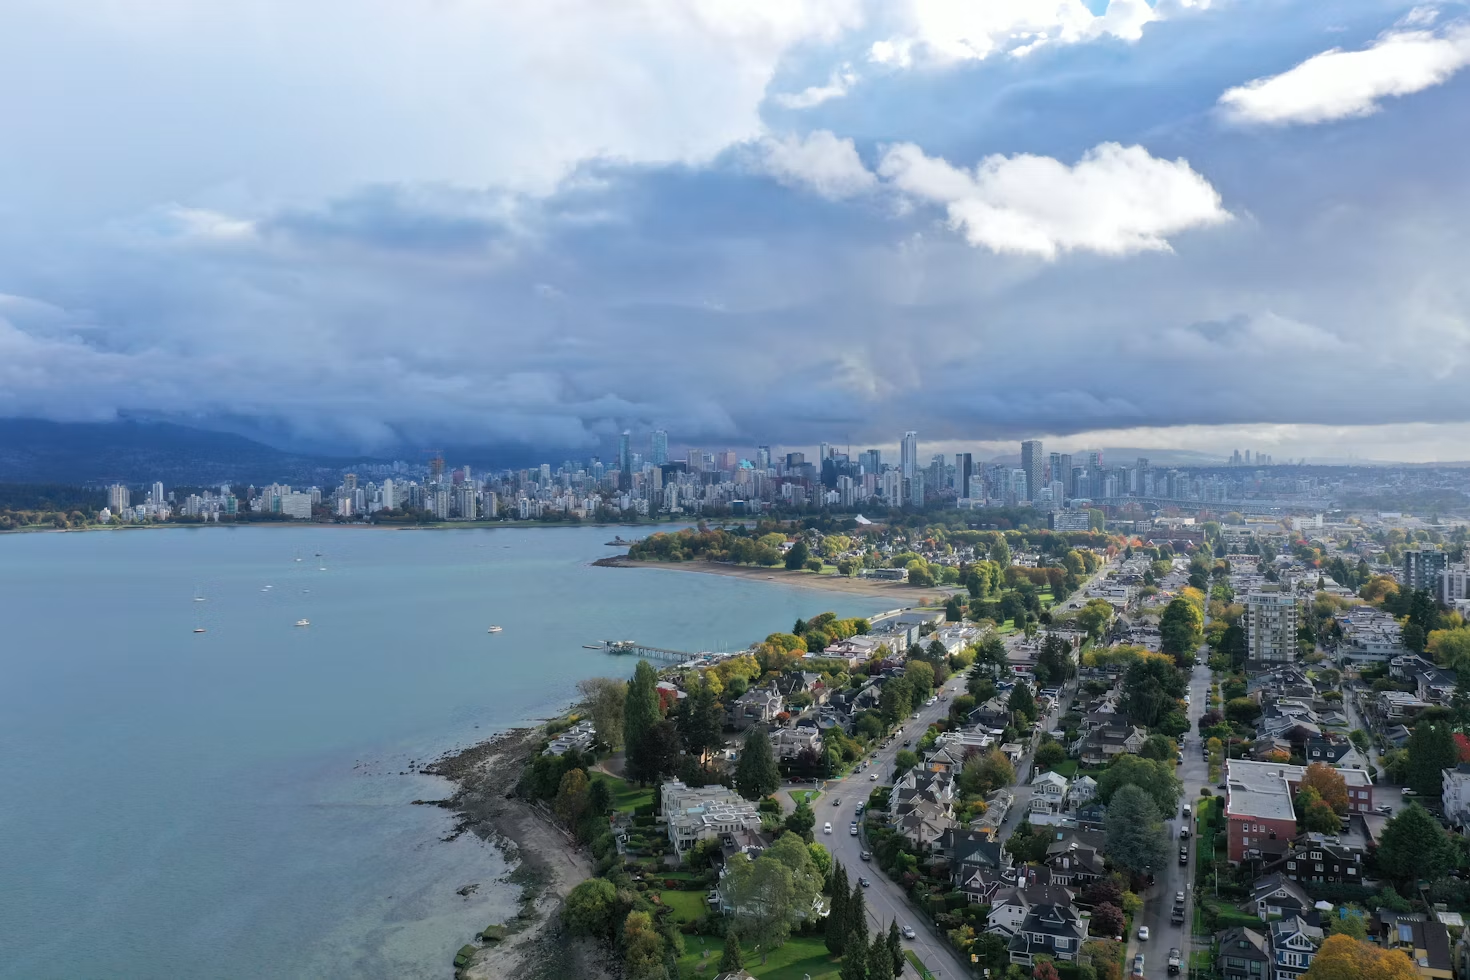
Vancouver, BC
Borrowing Costs Still Limit Demand
The Bank of Canada held its policy rate at 2.25% on July 15, its sixth consecutive rate announcement without a change. CREA also reported that fixed mortgage rates had eased from their April peak.
Borrowing costs nevertheless remain high enough to constrain affordability. The recent improvement in resale activity has therefore occurred without the substantial financing relief that could support a stronger national recovery.
New Construction Is Becoming a Larger Concern
Residential construction is moving in a less encouraging direction. CMHC’s June housing-starts data showed the six-month trend in starts falling 2.8% from May. Actual starts in centres with at least 10,000 residents were 13% below June 2025, while the year-to-date total was down 1%.
CMHC’s latest baseline forecast calls for 241,400 housing starts nationwide in 2026, down from 259,028 in 2025. The weakest construction outlook is concentrated in Ontario and British Columbia, with condominium development facing particular pressure as unsold inventory and high construction costs limit new projects.
Rental construction is also expected to moderate after reaching a historic peak in 2025. At the same time, new purpose-built rental supply and condominium units entering the secondary rental market are easing conditions in several major cities, particularly Toronto and Vancouver.
The slowdown could carry implications beyond the current market. CMHC expects some housing demand now constrained by affordability to return later in its forecast period. Fewer projects moving forward today would leave a thinner supply pipeline if demand strengthens in the years ahead.
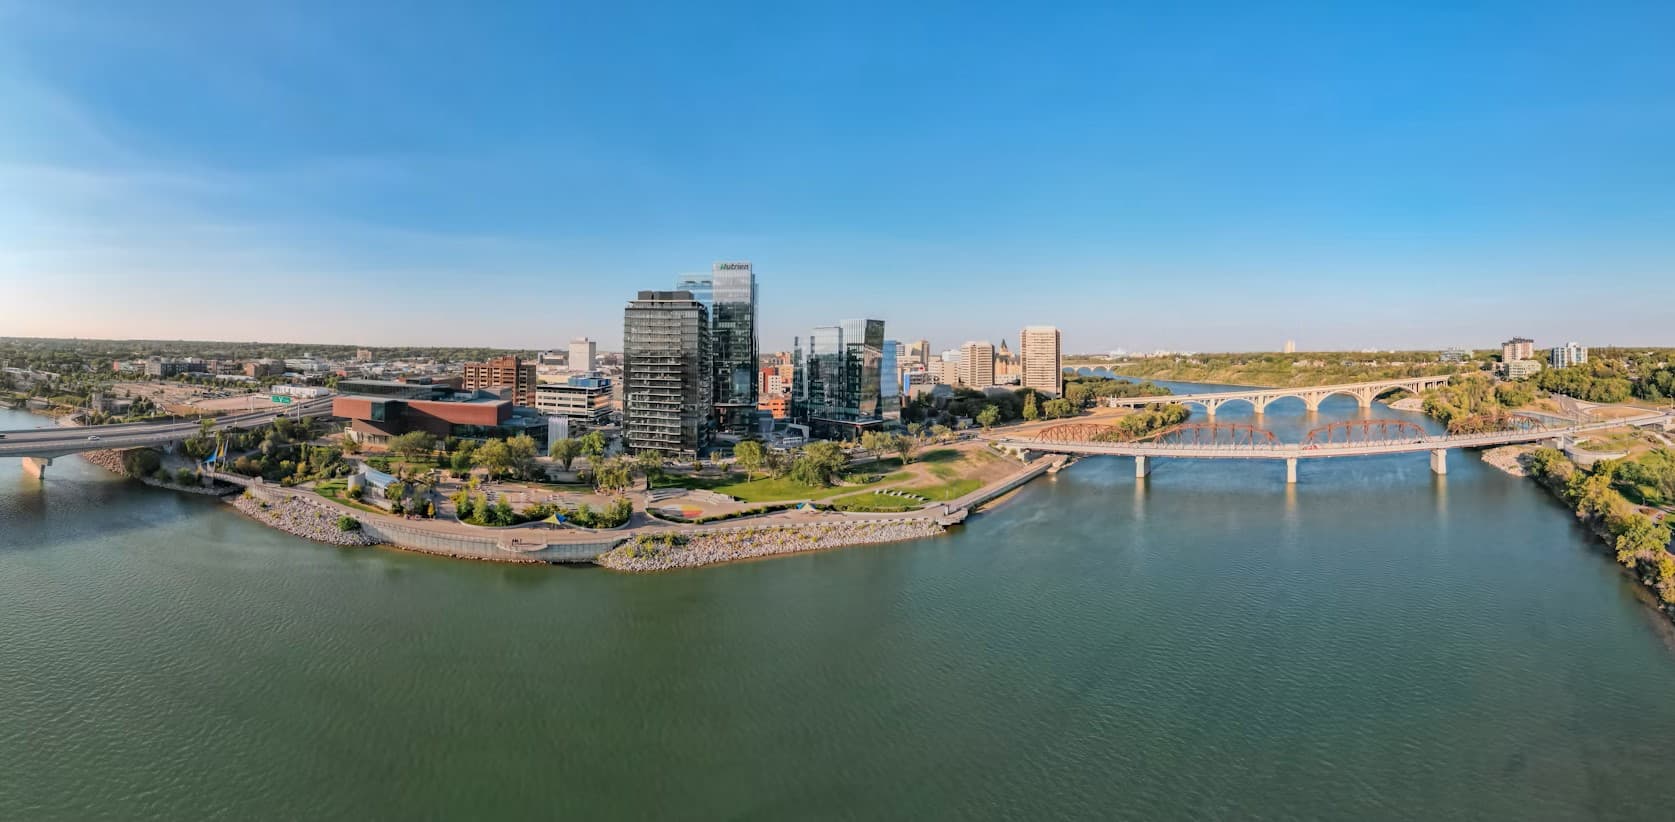
Saskatoon, SK
A More Stable Resale Market With a Weaker Supply Pipeline
Canada’s resale market is steadier than it was in early spring. Sales have recovered from their March low, benchmark prices stopped falling month over month in June, and available supply is close to historical norms.
The construction outlook is moving in the opposite direction. CREA and CMHC also remain divided on whether national average prices will finish 2026 slightly higher or lower, leaving the second half of the year defined more by stabilization than by a broad recovery.












