
New York City
National Trends
By late July, the U.S. housing market was telling a shifting story. Inventory levels surged, price gains cooled to multi-year lows, and regional trends became more pronounced, yet challenges with affordability and mortgage rates continued to temper momentum. These changes point to a gradual shift from the blistering seller’s market of recent years toward a more sustainable and balanced environment.
Realtor.com reports that inventory rose sharply, with homes for sale up 24.8% compared to last year, marking the 21st consecutive month of growth. For the third month in a row, active listings exceeded one million, though the total remained roughly 13.4% below pre-pandemic norms. This steady expansion in supply has given buyers more choice and negotiating leverage, although overall inventory still trails historic levels.
Price growth continued to ease. The S&P CoreLogic Case-Shiller U.S. National Home Price Index showed a 2.3% annual increase in May, down from 2.7% in April and representing the slowest pace since July 2023. The 20-City Composite recorded a 2.8% year-over-year gain, with notable differences across metros—New York led with a 7.4% increase, while Tampa prices fell 2.4%. Seasonally adjusted figures showed a 0.3% month-over-month decline, extending a pattern of cooling price momentum.
SUBSCRIBE TO THE HAVEN MAILING LIST
Curated homes, market intelligence and design stories — a few emails a month.
No spam. Unsubscribe any time.
The national numbers masked significant regional variation. According to Realtor.com, in July, 33 of the 50 largest metro areas recorded year-over-year list price declines, with 19 markets now listing below their July 2022 peaks. Inventory gains were most pronounced in the West, up 32.5%, and the South, up 25.4%, while the Midwest and Northeast posted smaller increases of 18.1% and 15.5%, respectively. Markets such as Miami, Austin, and Los Angeles have seen clear signs of cooling, with prices adjusting downward and listings rising. Meanwhile, parts of the Northeast and Midwest have maintained more stable conditions, benefiting from steady demand and less speculative volatility.
Mortgage Rates and Affordability
Mortgage rates remained a headwind. Throughout July, the average 30-year fixed rate hovered near 7%, according to Freddie Mac’s Primary Mortgage Market Survey, discouraging some prospective buyers and keeping many homeowners from listing due to the loss of their lower-rate loans. Even with slower price growth, affordability challenges persisted. The National Association of Realtors’ Housing Affordability Index fell to 97.2 in May, reflecting the combined pressure of elevated home prices and borrowing costs, which has been especially burdensome for first-time buyers.
In Focus: New York City
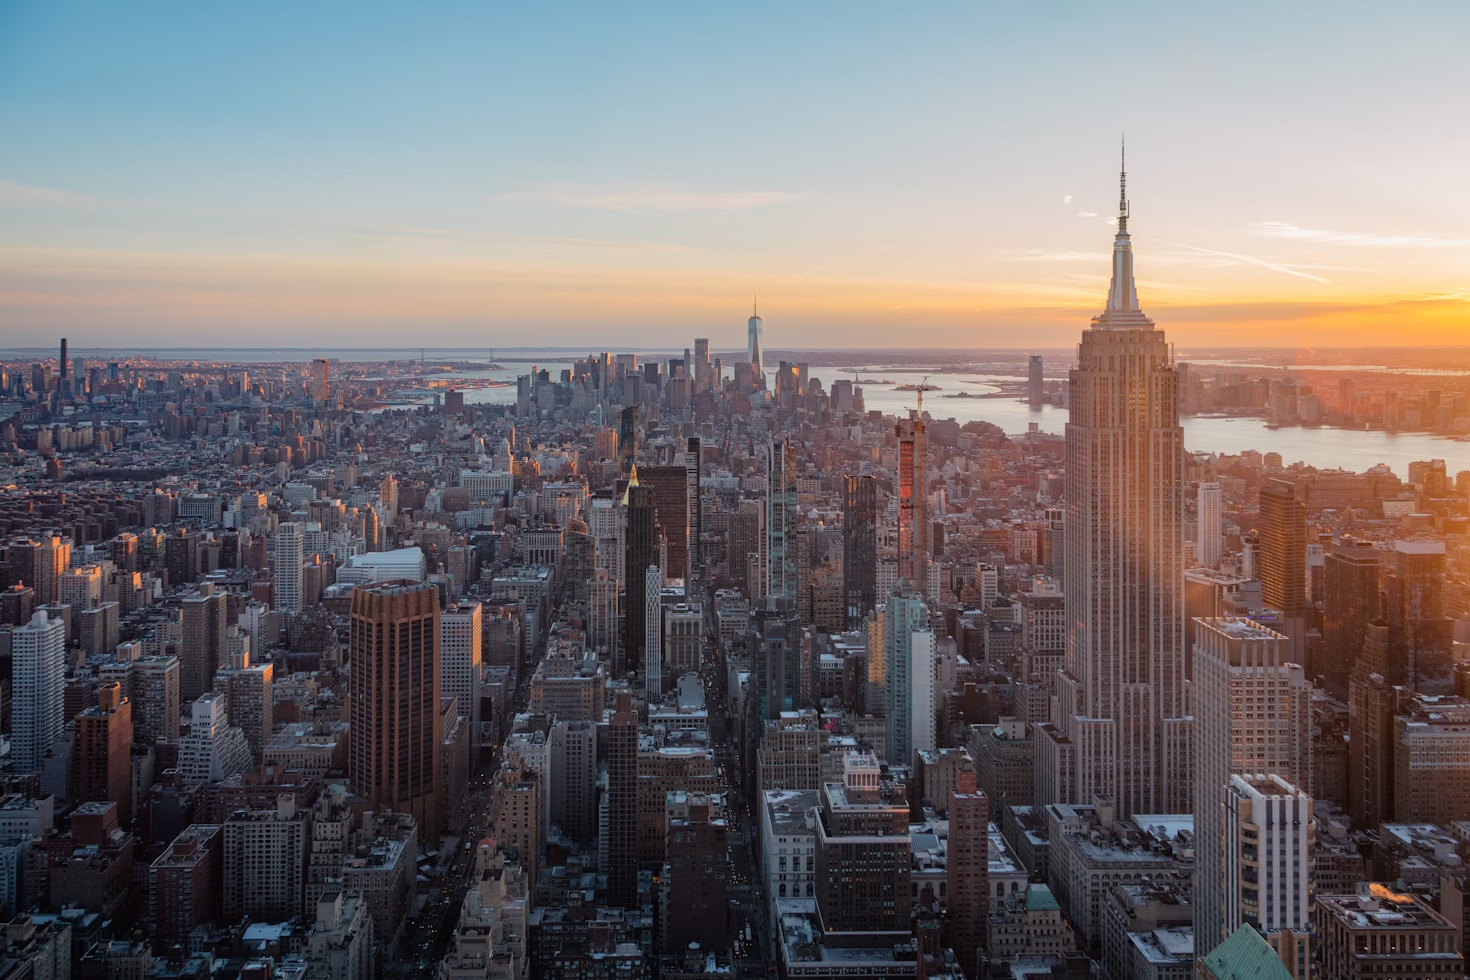
We got input from four local New York City realtors to provide insight into the city’s real estate landscape last month. There, July’s housing market reflected stability with selective activity. Inventory ticked up slightly in some neighborhoods, giving buyers modest leverage, while prices remained largely steady, with small gains in highly constrained areas such as downtown Manhattan, according to Robert Rahmanian of REAL New York. Douglas Wagner of BOND New York observed that primary residences below $2 million drew the most activity, with multiple bids on well-priced apartments, while cash buyers often prevailed. Nicole Gary of Keller Williams NYC stated that luxury properties with unique features or outdoor space remained strong, and buyers overall were acting strategically.
Across the city, sellers are adjusting expectations, and buyers are taking a more deliberate approach. As Rahmanian put it, “August should look similar to July overall: selective but active, with buyers closely watching value,” while Melissa Leifer of Keller Williams NYC said, “August can be a great time to get something, because you have frustrated sellers who have been on the market a long time.” Gary also noted that there has been increasing interest from international buyers, particularly buyers from Europe, because the euro-to-dollar exchange rate is strong at the moment.
Key Takeaways
The market data from July suggests that housing in the United States is moving toward a new equilibrium after years of extreme conditions. Rising inventory and decelerating price growth signal progress toward balance, while the persistent influence of high mortgage rates and affordability constraints indicates that the transition will be gradual. For buyers, the expanding pool of available homes offers more room to be selective. For sellers, realistic pricing, strong presentation, and adaptability to changing conditions are increasingly essential in an environment where competition among listings is intensifying.












